Financial literacy • Money skills • Young adults • Financial confidence • Life skills
By Carrie-Ann McLean | Author
Young Australians are making financial decisions earlier than we sometimes realise.
They may have a bank account and debit card before they have their first job. They can shop online in seconds, sign up for subscriptions, use digital payments, see Buy Now Pay Later offers at checkout and be exposed to constant messages about what they should own, wear and spend.
Then adulthood brings a whole new set of decisions – earning an income, reading a payslip, paying bills, saving, managing debt, understanding tax and superannuation, and working out how to make limited money stretch across competing priorities.
These are practical life skills.
Young people don’t need to know everything about money before they reach adulthood. But giving them a strong foundation can help them make more informed decisions, avoid some costly mistakes and, importantly, build confidence in their ability to manage money.
What money skills do young Australians need before adulthood?
Financial literacy isn’t just about understanding financial terminology or being good at maths.
It’s about knowing how to use money in everyday life.
Before adulthood, young people can benefit from learning how to:
- manage income and create a realistic budget
- understand the difference between needs, wants and priorities
- set savings goals and build an emergency buffer
- use bank accounts, cards and digital payments responsibly
- understand credit, debt and Buy Now Pay Later
- recognise impulse spending, advertising and peer pressure
- understand the basics of earning, tax and superannuation
- make informed financial decisions
- know what to do when money doesn’t go according to plan
- talk about money and ask for help without embarrassment or shame
The goal isn’t to create financial experts at 18.
It’s to help young people enter adulthood with practical skills, greater awareness and the confidence to ask questions when they don’t understand something.
Why practical money skills matter before adulthood
Financial independence doesn’t usually arrive all at once.
It happens gradually.
A teenager gets their first casual job. They begin managing their own bank account. They might start paying for their phone or transport. They go out with friends. They buy things online. They start driving. They may move into university, TAFE, an apprenticeship or full-time work.
Eventually, they may begin thinking about moving out of home.
With each step comes more responsibility for making decisions about money.
At the same time, spending has become incredibly easy. A purchase can take seconds. Money can leave an account with a tap of a card or phone. Subscriptions can continue unnoticed, and Buy Now Pay Later can make something appear affordable because the full cost isn’t leaving the account today.
Practical financial literacy helps young people understand what’s happening behind those transactions and think about the effect their decisions may have tomorrow as well as today.
1. How to manage money coming in
One of the most useful money lessons a young person can learn is simple:
Having money available doesn’t mean all of it is available to spend.
Think about receiving your first pay.
If $300 lands in your bank account, it can be tempting to see $300 available and think, I’ve got $300 to spend.
But what else does that money need to do?
Perhaps some needs to go towards transport or a phone bill. Maybe you’re saving for a car, a laptop or something else important to you. You might want some money available to go out with friends.
That’s where learning to budget becomes useful.
At Budget Right, I use a simple 70/10/10/10 cash flow approach as a starting point:
70% – Needs & Lifestyle
10% – Savings
10% – Giving
10% – Fun or Splash Cash
The exact percentages won’t suit every person or every stage of life – and they don’t have to.
The bigger lesson is learning to give your money a purpose.
A budget shouldn’t make you feel as though you’re being punished for spending money. It helps you decide what matters to you and make choices accordingly.
Learning that with your first few pays can establish habits that continue long after your first job.
2. The difference between needs, wants and priorities
Young people are growing up surrounded by opportunities and encouragement to spend.
Social media, influencers, advertising, online shopping and one-click payments can make buying something feel almost effortless.
There is also the pressure that can come from seeing what friends are wearing, buying, driving or doing.
That’s why simply telling a young person to “stop spending” isn’t particularly helpful.
A much more useful skill is learning to pause and ask:
- Do I need this?
- Do I want this?
- Can I afford this?
- What am I giving up if I buy it?
That last question is particularly important.
Most of us don’t have unlimited money. Choosing one thing can mean delaying something else.
Spending $100 isn’t automatically a bad decision. But if that $100 was supposed to help pay your car registration next month, the decision looks different.
Financial confidence grows when young people learn to make those trade-offs based on their own priorities rather than automatically following what friends, advertising or social media suggest they should have.
3. How to save, and why an emergency buffer matters
“Save your money” is advice many young people hear.
But telling someone to save isn’t the same as teaching them how to save.
A big goal can feel impossible until it’s broken into smaller amounts.
Imagine wanting something that costs $600.
Rather than thinking, I’ll never have $600, you can work backwards.
If you want to reach the goal in six months, how much would you need to put aside each month, fortnight or week?
Suddenly, $600 becomes a series of smaller decisions.
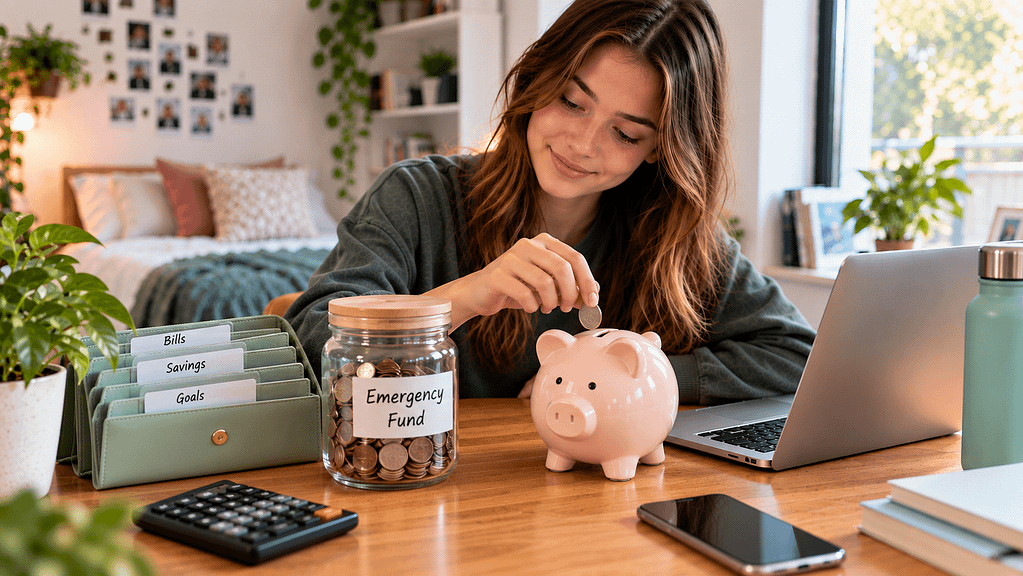
Young people can also benefit from understanding the purpose of an emergency buffer.
For someone starting out, I like the idea of working towards a first $500 emergency buffer. From there, it can gradually grow as income, expenses and responsibilities increase.
An emergency buffer isn’t only about having money sitting in a bank account.
It’s breathing room.
When something unexpected happens, having even a small amount set aside can provide another option before immediately turning to debt or giving up on other financial goals.
4. How bank accounts, cards and digital spending work
Money has become less visible.
When you hand over a $20 note, you physically see the money leave your hand.
When you tap a phone or card, that feeling is very different.
The transaction can be over before you’ve really thought about it.
That’s why young people need practical experience with things such as transaction and savings accounts, debit and credit cards, automatic payments, subscriptions, account fees and charges, banking security and checking transactions.
It is also important to understand what happens when there isn’t enough money in an account and why regularly checking where money has gone matters.
These may sound like small things.
But everyday financial confidence is built through small things.
Knowing how your bank account works, recognising a transaction, noticing a subscription you no longer use and understanding the difference between spending your own money and borrowing money all contribute to becoming a more confident money manager.
5. What debt really costs
Debt can make something affordable today by moving some or all of the cost into the future.
That’s exactly why young people need to understand it.
Credit cards, personal loans and Buy Now Pay Later arrangements can all affect future cash flow.
The lesson shouldn’t simply be:
Debt is bad.
A more useful conversation is about understanding what you’re agreeing to.
How much will you need to repay?
Are there fees or interest?
How long will you be making repayments?
What happens if you miss one?
And what else will those repayments prevent you from doing with your future income?
One question I think is particularly valuable is:
If I use tomorrow’s money to buy something today, what will that mean for tomorrow’s budget?
It turns debt from an abstract concept into something much easier to understand.
Tomorrow’s pay may already have a job before it even reaches your account.
6. How emotions and peer pressure affect spending
This is one of the money skills I believe deserves far more attention.
Money decisions aren’t purely mathematical.
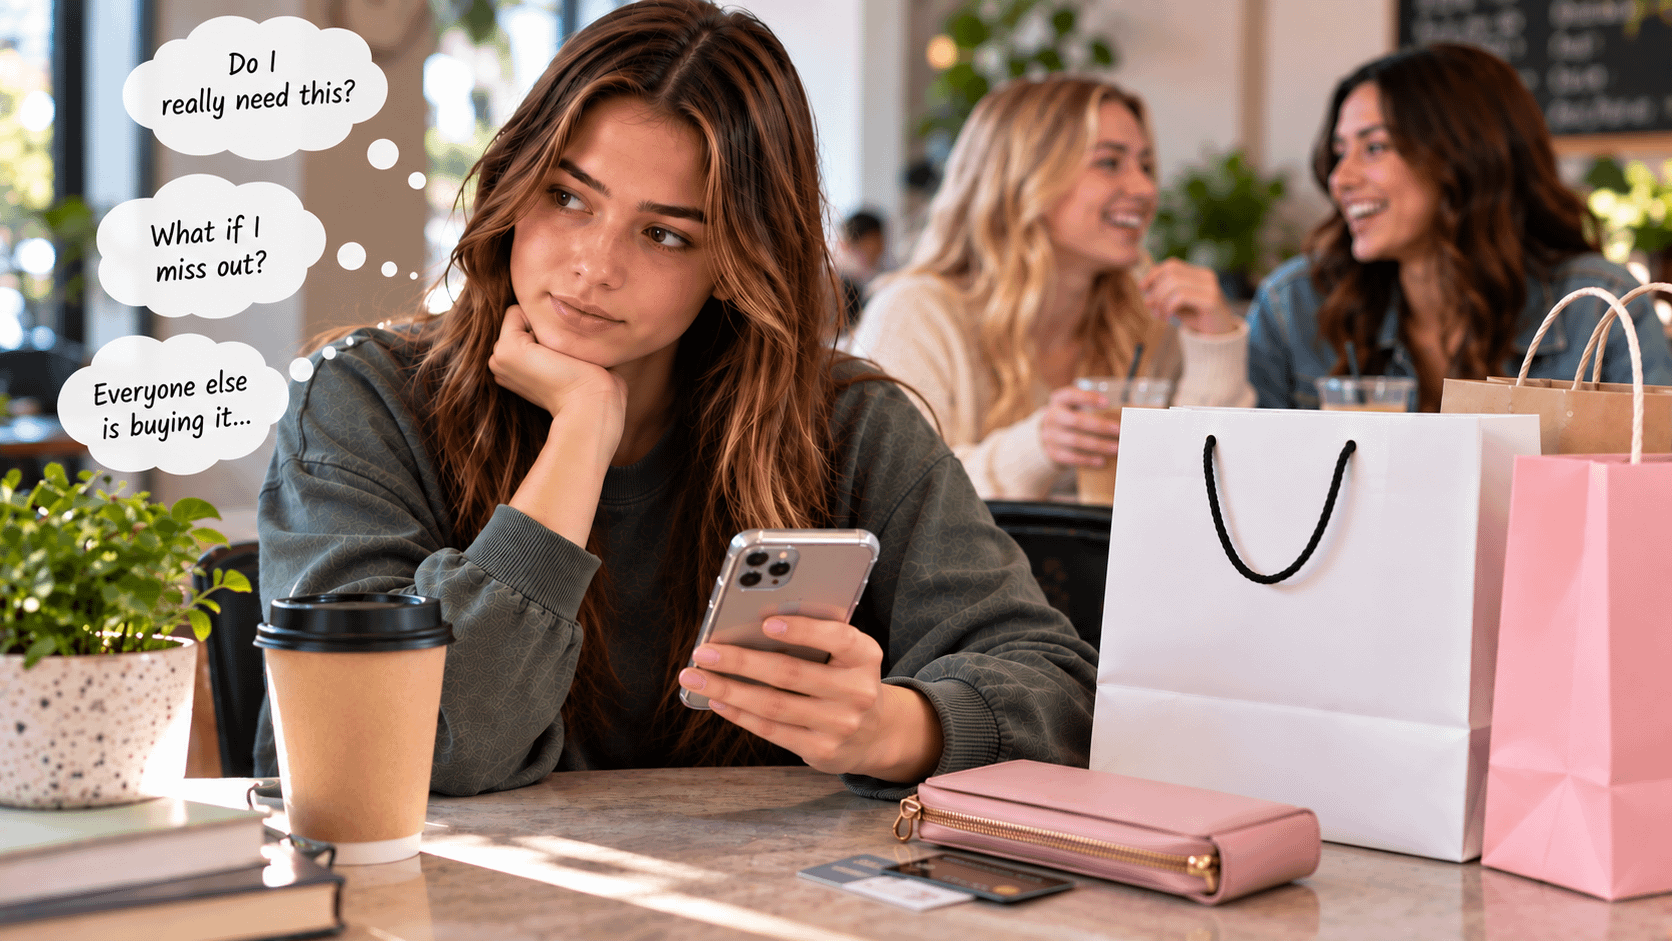
Sometimes we spend because we’re bored.
Sometimes we’re having a bad day and buying something gives us a temporary lift.
Sometimes our friends are going somewhere or buying something and we don’t want to be left out.
Sometimes advertising creates a sense of urgency or makes us feel as though we’re missing out.
And sometimes we don’t really know why we spent the money until afterwards.
Understanding these influences is part of financial literacy too.
Young people can learn to recognise their own spending triggers and create a pause between feeling something and buying something.
They can also learn that it’s okay to say:
“That’s not in my budget this week.”
That isn’t something to be embarrassed about.
In fact, being able to make a decision based on what you can afford rather than what other people are doing is a sign of financial confidence.
Money management isn’t just about understanding numbers.
It’s also about understanding ourselves.
7. The basics of earning, tax and superannuation
A first job brings far more than a first pay.
It introduces a young person to a whole new financial vocabulary.
What is gross pay?
Why is the amount deposited into the bank different?
What does a payslip show?
What is income tax?
What is a Tax File Number?
What is superannuation, and where does that money go?
What are hourly rates and penalty rates?
These are practical questions that become very real when someone starts earning their own money.
Young people don’t need to become experts in Australia’s tax or superannuation systems.
But they should feel comfortable reading a payslip, checking that something looks right, understanding where their money is going and knowing where to find reliable information or ask for help when they’re unsure.
That knowledge can make a first job feel much less overwhelming.
8. What to do when things go wrong
There is one more financial skill I want young people to learn before adulthood:
You don’t have to manage money perfectly.
Because none of us does.
Budgets go off track.
Unexpected expenses happen.
We buy things we regret.
We forget about bills.
Our circumstances change.
The important skill is knowing what to do next.
Look at what happened. Ask for help if you need it. Adjust your plan. Take the next practical step. Keep going.
A money mistake doesn’t need to become a bigger financial problem. Looking at what happened and taking the next practical step can help you move forward.
That is why financial resilience matters alongside financial literacy.
Financial resilience isn’t about never experiencing a setback. It’s about developing the skills and confidence to respond when one happens.
Money conversations matter too
There is another money skill that is easy to overlook – being able to talk about it.
Money can be uncomfortable.
Young people may be reluctant to admit they don’t understand something because they think everyone else already knows. They may feel embarrassed if they can’t afford what their friends can afford. They may make a financial mistake and hide it because they’re worried about being judged.
That’s why the way we talk about money matters.
Instead of making money conversations about getting everything right, we can make them about curiosity.
- What happened?
- What could you do differently next time?
- Is there something you don’t understand?
- Where could you get reliable information?
- Who could you ask for help?
Being comfortable enough to ask those questions is a financial skill in itself.
We don’t need young people to be perfect with money
When I talk about financial literacy, I’m not talking about creating teenagers who never impulse buy, never make a money mistake and have their entire financial future planned by 18.
That’s unrealistic.
I didn’t learn many of the money-management skills I use today until much later in my own life.
That’s one reason I’m so passionate about giving young people practical knowledge earlier.
Imagine reaching adulthood already understanding how to create a budget, manage your first pay, save towards a goal, recognise the real cost of debt, understand your spending triggers and knowing where to turn when you need help.
It won’t guarantee that every financial decision will be the right one.
But it provides something incredibly valuable.
A starting point.
From financial literacy to financial confidence
Ultimately, the goal isn’t just financial literacy.
- It’s financial confidence.
- It’s receiving your first pay and having a plan for it.
- It’s knowing the difference between the balance in your bank account and the amount you can actually afford to spend.
- It’s understanding what you’re agreeing to before taking on debt.
- It’s being able to compare choices instead of simply following what everyone else is doing.
- It’s knowing that a money mistake can be corrected.
- And it’s feeling comfortable enough to ask a question when you don’t understand something.
We can’t prepare young people for every financial decision they’ll face.
But we can give them practical skills and a stronger foundation from which to make those decisions.
The earlier we start those conversations, the more opportunity young Australians have to build financial confidence before they’re managing everything on their own.
Helping young Australians build practical, life-ready money skills
Learning to manage money doesn’t happen all at once. It develops through conversations, experience and having practical information to turn to when new financial decisions arise.
That’s why I wrote Money, Sorted. Life, Ready. – Budget Right for Young Adults.
Created for young people aged 16–23, the book covers the everyday money skills that matter as they move towards greater independence – from budgeting, saving and managing their first income to understanding debt, spending habits, bank accounts and making confident money decisions.
It isn’t about having money completely figured out.
It’s about giving young people a practical place to start.
Learn more about Money, Sorted. Life, Ready. and the practical money skills it can help young adults build.
Budget Right provides financial education and general information only. It does not provide personal financial advice. Consider your own circumstances and seek professional advice where appropriate.
About the Author
Carrie-Ann McLean is an Author, Speaker, Budgeting Coach and Money Mindset Educator who helps everyday Australians improve their financial wellbeing without guilt, shame or overwhelm.
Drawing on her own lived experience of rebuilding her life after addiction, homelessness and significant debt, Carrie-Ann combines practical budgeting strategies with compassionate money mindset education to help people build lasting financial confidence.
She is the founder of Budget Right and the author of Budget Right: Eliminate Debt and Improve Your Financial and Mental Wellbeing and Money, Sorted. Life, Ready.
Disclaimer
This article is intended for general educational purposes only and does not constitute financial, legal or accounting advice. Please seek independent professional advice that considers your personal circumstances before making financial decisions.